Popular on TelAve
- Geospatial Innovation Comes to Sacramento: FOSS4G NA 2026 - 248
- LowSignalMail Lets Users Handle Gmail by Text Message - 201
- Coinfiliate Launches Platform to Helps Shoppers Earn Cashback and Creators Earn Referral Rewards - 148
- TechMinds Files CRTC Application Challenging Rogers and Bell Over Wholesale Internet Practices - 128
- Claude Zdanow named Managing Director in Miami, Florida - 109
- RAS AP Consulting Issues National Compliance Alert and Launches Q4 2026 AP Readiness Program Ahead of IRS FIRE → IRIS Cutover - 106
- Evergreen Surety Launches Telecommunications Surety Bonds Page as Broadband and 5G Buildout Expands Obligee Requirements - 105
- Nextlink Internet Deploys netElastic to Modernize Its Hybrid Broadband Network - 105
- Commercial Manufacturing Validation Completed as November 10 FDA Milestone Approaches; Critical FDA Milestone Close: NRx Pharmaceuticals NAS DAQ: NRXP
- Pregis Launches Sharp InfinX: On-Demand Rightsized Mailing System Delivering a Precision-Sized Mailer for Every Order
First Bancorp of Indiana, Inc. Announces Financial Results - September 30 2026
TelAve News/10911222
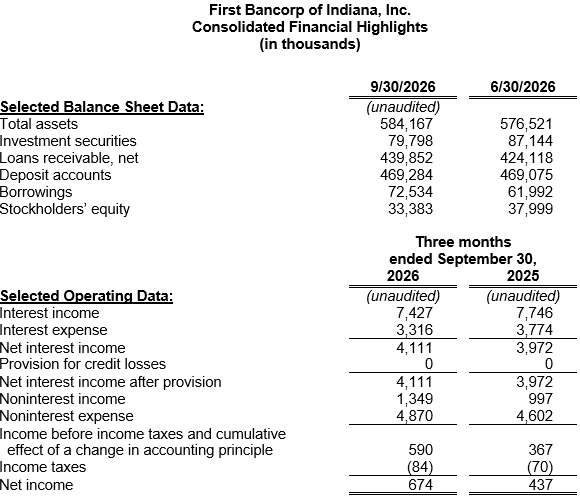
EVANSVILLE, Ind. - TelAve -- First Bancorp of Indiana, Inc. (OTCPK:FBPI), the holding company (the "Company") for First Federal Savings Bank (the "Bank"), reported earnings of $674,000 ($0.39 per diluted common share) for the first fiscal quarter ended September 30, 2026, compared to $437,000 ($0.26 per diluted common share) for the same quarter a year ago. Earnings for the three-month period equate to a return on average assets ("ROAA") of 0.47% and a return on average equity ("ROAE") of 7.27%. This compares to an annualized ROAA of 0.29% and an annualized ROAE of 5.21% for the prior year quarter.
"Our first-quarter results reflect continued progress in managing the cost and composition of our funding," stated Michael H. Head, President and CEO. "Stable deposits, reduced reliance on higher-cost brokered deposits, and continued development of core and public funds relationships contributed to lower funding costs and improved net interest margin."
Net interest income for the quarter ended September 30, 2026, improved from the same timeframe last fiscal year. The Company's focus on lowering funding costs more than offset reduced interest income from loans and investments. The Company's net interest margin ("NIM"), measured as a percentage of average interest-earning assets, improved to 3.10% from 2.86% for the prior-year quarter. Noninterest income increased by 35.3% during the most recent quarter, driven by higher service charge income and proceeds from a life insurance claim. Noninterest expense also increased, primarily reflecting higher compensation costs, data processing charges, and professional fees.
The securities portfolio, composed primarily of investment-grade municipal bonds and obligations of U.S. government agencies, totaled $79.8 million at September 30, 2026, compared with $87.1 million at the beginning of the fiscal year. In addition to routine principal repayments, the decrease primarily reflected an increase in the unrealized loss on the Bank's available-for-sale securities portfolio resulting from the recent rise in long-term interest rates.
Net loans outstanding totaled $439.9 million at September 30, 2026, an increase of $15.7 million, or 3.7%, during the quarter. Commercial loan production totaled $15.2 million for the quarter. Single-family mortgage loan production, consisting primarily of loans originated for sale to Fannie Mae or the Federal Home Loan Bank, totaled $5.1 million. Consumer loan originations, including automobile, personal, and home equity loans and lines of credit, totaled $6.2 million.
More on TelAve News
No provision for credit losses on loans was recorded in the three months ended September 30, 2026 or 2025. Net loan charge offs totaled $234,900 for the current quarter, compared to $32,700 for the comparative quarter last year. The ratio of nonperforming loans 90 days or more delinquent to total loans was 0.27% on September 30, 2026, compared to 0.29% a year ago.
The allowance for credit losses, including reserves for investment securities and unfunded commitments, stood at $5.11 million at September 30, 2026, compared to $5.28 million on September 30, 2025. The portion of the allowance attributed to the loan portfolio represented 1.12% of at-risk loans on September 30, 2026, compared to 1.13% last year. Management considers the allowance appropriate under current conditions. However, high energy prices, rising interest rates, and elevated inflation could adversely affect borrowers and the credit quality of the loan portfolio. In response, management continues to closely monitor borrowers most affected by these challenges and stands ready to adjust the allowance as needed to address emerging risks.
Total deposit accounts, totaling $469.3 million on September 30, 2026, remained stable from the beginning of the fiscal year, while the Bank continued to retire higher cost brokered deposits. Although local deposit competition has increased in recent months as Treasury rates rose, the focus on core deposits and public funds relationships helped reduce the cost of deposits to 2.32% for the current quarter compared to 2.56% for the same quarter last fiscal year. Similarly, the Company's total cost of funds, including FHLB advances and debt of the holding company, totaled 2.52% for the quarter, compared with 2.70% for the quarter ended September 30, 2025.
As part of the Bank's liquidity management plan, management maintains diversified contingent funding sources and performs liquidity stress testing to assess funding adequacy. At September 30, 2026, the Bank had $22.5 million of unused lines of credit with correspondent financial institutions. Additional secured borrowing capacity included $16.9 million through the Federal Reserve Bank's discount window and $115.6 million through the Federal Home Loan Bank.
Stockholders' equity totaled $33.4 million on September 30, 2026, compared with $35.7 million at September 30, 2025. The year-over-year decline was primarily the result of an increase in the unrealized loss on the Bank's available-for-sale securities portfolio. Based on the 1,712,058 outstanding common shares on September 30, 2026, the tangible book value per share of FBPI stock was $15.86, compared to $17.28 on September 30, 2025.
More on TelAve News
On September 30, 2026, First Federal Savings Bank's Community Bank Leverage Ratio ("CBLR") was 9.63%. At September 30, 2025, the Bank reported a Tier 1 leverage ratio of 8.92%.
At its October meeting, the Board of Directors of First Bancorp of Indiana, Inc. declared a cash dividend of $0.08 per share, payable to stockholders of record as of December 1, 2026. The dividend will be paid on or about December 15, 2026. While it is the Board's intent to pay a regular quarterly dividend, the payment of any future dividends will be subject to, among other factors, the Company's and the Bank's financial condition, earnings, and capital requirements.
This press release may contain statements that are forward-looking, as that term is defined by the Private Securities Litigation Act of 1995 or the Securities and Exchange Commission in its rules, regulations and releases. The Company intends that such forward-looking statements be subject to the safe harbors created thereby. All forward-looking statements are based on current expectations regarding important risk factors including, but not limited to: general economic conditions; prices for real estate in the Company's market areas; the interest rate environment and the impact of the interest rate environment on our business, financial condition and results of operations; our ability to successfully conserve and enhance capital levels, enhance liquidity and earnings, and reduce higher funding costs; the Company's ability to pay future dividends; the Bank's ability to pay dividends to the Company to fund the payment of cash dividends on the Company's common stock, and the ability of the Bank to receive any required regulatory approval or non-objection to do so; changes in the demand for loans or in the quality or composition of our loan or investment portfolios; deposits and other financial services that we provide; the possibility that future credit losses may be higher than currently expected as a result of changes in relevant accounting or regulatory requirements, among other factors; competitive pressures among financial services companies; the ability to attract, develop and retain qualified employees; our ability to maintain the security of our data processing and information technology systems; the outcome of pending or threatened litigation, or of matters before regulatory agencies; changes in law, governmental policies and regulations; and rapidly changing technology affecting financial services. Accordingly, actual results may differ from those expressed in the forward-looking statements, and the making of such statements should not be regarded as a representation by the Company or any other person that results expressed therein will be achieved. The Company undertakes no obligation to release revisions to these forward-looking statements publicly to reflect events or circumstances after the date hereof or to reflect the occurrence of unforeseen events, except as required to be reported by applicable law.
"Our first-quarter results reflect continued progress in managing the cost and composition of our funding," stated Michael H. Head, President and CEO. "Stable deposits, reduced reliance on higher-cost brokered deposits, and continued development of core and public funds relationships contributed to lower funding costs and improved net interest margin."
Net interest income for the quarter ended September 30, 2026, improved from the same timeframe last fiscal year. The Company's focus on lowering funding costs more than offset reduced interest income from loans and investments. The Company's net interest margin ("NIM"), measured as a percentage of average interest-earning assets, improved to 3.10% from 2.86% for the prior-year quarter. Noninterest income increased by 35.3% during the most recent quarter, driven by higher service charge income and proceeds from a life insurance claim. Noninterest expense also increased, primarily reflecting higher compensation costs, data processing charges, and professional fees.
The securities portfolio, composed primarily of investment-grade municipal bonds and obligations of U.S. government agencies, totaled $79.8 million at September 30, 2026, compared with $87.1 million at the beginning of the fiscal year. In addition to routine principal repayments, the decrease primarily reflected an increase in the unrealized loss on the Bank's available-for-sale securities portfolio resulting from the recent rise in long-term interest rates.
Net loans outstanding totaled $439.9 million at September 30, 2026, an increase of $15.7 million, or 3.7%, during the quarter. Commercial loan production totaled $15.2 million for the quarter. Single-family mortgage loan production, consisting primarily of loans originated for sale to Fannie Mae or the Federal Home Loan Bank, totaled $5.1 million. Consumer loan originations, including automobile, personal, and home equity loans and lines of credit, totaled $6.2 million.
More on TelAve News
- New Patient Data Show REQORSA® Activating Cellular Repair Pathways as Roche Collaboration Advances Precision Lung Cancer Strategy for Genprex, Inc
- Genuine Hospitality, LLC Selected to Operate Holiday Inn Express & Suites Jacksonville – Town Center
- Shiokly Launches Online Marketplace to Help Singapore Home-Based Businesses Sell More, With First Product Listed Free
- Freight Broker 911 and Milton Collier Introduce "What's The 911?"—A New Podcast Built on Real Talk, Real Freight, and Real Opportunity
- CONNECTSIM Highlights Thailand eSIM Plans as Dry Season Opens and Loy Krathong Approaches
No provision for credit losses on loans was recorded in the three months ended September 30, 2026 or 2025. Net loan charge offs totaled $234,900 for the current quarter, compared to $32,700 for the comparative quarter last year. The ratio of nonperforming loans 90 days or more delinquent to total loans was 0.27% on September 30, 2026, compared to 0.29% a year ago.
The allowance for credit losses, including reserves for investment securities and unfunded commitments, stood at $5.11 million at September 30, 2026, compared to $5.28 million on September 30, 2025. The portion of the allowance attributed to the loan portfolio represented 1.12% of at-risk loans on September 30, 2026, compared to 1.13% last year. Management considers the allowance appropriate under current conditions. However, high energy prices, rising interest rates, and elevated inflation could adversely affect borrowers and the credit quality of the loan portfolio. In response, management continues to closely monitor borrowers most affected by these challenges and stands ready to adjust the allowance as needed to address emerging risks.
Total deposit accounts, totaling $469.3 million on September 30, 2026, remained stable from the beginning of the fiscal year, while the Bank continued to retire higher cost brokered deposits. Although local deposit competition has increased in recent months as Treasury rates rose, the focus on core deposits and public funds relationships helped reduce the cost of deposits to 2.32% for the current quarter compared to 2.56% for the same quarter last fiscal year. Similarly, the Company's total cost of funds, including FHLB advances and debt of the holding company, totaled 2.52% for the quarter, compared with 2.70% for the quarter ended September 30, 2025.
As part of the Bank's liquidity management plan, management maintains diversified contingent funding sources and performs liquidity stress testing to assess funding adequacy. At September 30, 2026, the Bank had $22.5 million of unused lines of credit with correspondent financial institutions. Additional secured borrowing capacity included $16.9 million through the Federal Reserve Bank's discount window and $115.6 million through the Federal Home Loan Bank.
Stockholders' equity totaled $33.4 million on September 30, 2026, compared with $35.7 million at September 30, 2025. The year-over-year decline was primarily the result of an increase in the unrealized loss on the Bank's available-for-sale securities portfolio. Based on the 1,712,058 outstanding common shares on September 30, 2026, the tangible book value per share of FBPI stock was $15.86, compared to $17.28 on September 30, 2025.
More on TelAve News
- PropAccount.com Launches PropWallet, Turning Prop Firm Payouts Into Repeat Sales
- KOLBUS America, For All Of Your Hycorr Equipment And Service Needs
- Heritage at Hopewell Announces New 3.875% Year-One Mortgage Rate Buydown Incentive on Quick Delivery Townhomes (7.11% APR)
- New TROP2 Research Breakthrough Strengthens REQORSA® Gene Therapy Story as Roche Collaboration Advances Precision Lung Cancer Treatment: Genprex, Inc
- Rent a Truck or Hire Movers? New Data Shows Fuel Now Makes Up to 40% of DIY Moving Costs
On September 30, 2026, First Federal Savings Bank's Community Bank Leverage Ratio ("CBLR") was 9.63%. At September 30, 2025, the Bank reported a Tier 1 leverage ratio of 8.92%.
At its October meeting, the Board of Directors of First Bancorp of Indiana, Inc. declared a cash dividend of $0.08 per share, payable to stockholders of record as of December 1, 2026. The dividend will be paid on or about December 15, 2026. While it is the Board's intent to pay a regular quarterly dividend, the payment of any future dividends will be subject to, among other factors, the Company's and the Bank's financial condition, earnings, and capital requirements.
This press release may contain statements that are forward-looking, as that term is defined by the Private Securities Litigation Act of 1995 or the Securities and Exchange Commission in its rules, regulations and releases. The Company intends that such forward-looking statements be subject to the safe harbors created thereby. All forward-looking statements are based on current expectations regarding important risk factors including, but not limited to: general economic conditions; prices for real estate in the Company's market areas; the interest rate environment and the impact of the interest rate environment on our business, financial condition and results of operations; our ability to successfully conserve and enhance capital levels, enhance liquidity and earnings, and reduce higher funding costs; the Company's ability to pay future dividends; the Bank's ability to pay dividends to the Company to fund the payment of cash dividends on the Company's common stock, and the ability of the Bank to receive any required regulatory approval or non-objection to do so; changes in the demand for loans or in the quality or composition of our loan or investment portfolios; deposits and other financial services that we provide; the possibility that future credit losses may be higher than currently expected as a result of changes in relevant accounting or regulatory requirements, among other factors; competitive pressures among financial services companies; the ability to attract, develop and retain qualified employees; our ability to maintain the security of our data processing and information technology systems; the outcome of pending or threatened litigation, or of matters before regulatory agencies; changes in law, governmental policies and regulations; and rapidly changing technology affecting financial services. Accordingly, actual results may differ from those expressed in the forward-looking statements, and the making of such statements should not be regarded as a representation by the Company or any other person that results expressed therein will be achieved. The Company undertakes no obligation to release revisions to these forward-looking statements publicly to reflect events or circumstances after the date hereof or to reflect the occurrence of unforeseen events, except as required to be reported by applicable law.
Source: First Bancorp of Indiana Inc
0 Comments
Latest on TelAve News
- Tampa Holiday Sessions: Captured by Mallary Opens 2026 Christmas Minis With Two New Sets
- Tampa Web Design Launches New Website for Entrepreneur and Capital Markets Advisor Martin Sumichrast
- Miami Dade College and World Affairs Council of Miami announce Navarro-Cabrera scholarship
- RPP to host first Professional Padel Week in Miami and announce the 2026 USA Awards winners
- UK Financial Ltd. Announces Maya Preferred PRA as First Fully Verified Asset on MAYA CHAIN; Chainlink Proof of Reserve Integration Planned for Network
- ALight Technology And Services Limited Advances Through Peachscore + Dealum Accelerator and Join LvlUp Labs
- International Misophonia Foundation Launches Sensory Accessible Technology Initiative to Address Overlooked Digital Accessibility Barriers
- KAIT to Demonstrate 400 Gbps 8K Video Processing via SRv6 In-Network Computing at SC26
- RAS AP Consulting Advances 1099 Education and Readiness Initiative Through IFOL Training and Finance Technology Showcase
- Heritage at Manalapan Announces New 3.875% First-Year Mortgage Rate Buydown (7.11 APR)
- AthleteMerch.com Surpasses 100,000 Custom Items Delivered to Fans Nationwide
- Steve Weclew is Appointed by STS Capital Partners as Managing Director
- New Finnish Affiliate Site Ilmaiskierrokset.com Puts Wager-Free Spins in the Spotlight
- Major FDA Victory; Preservative-Free Ketamine Approved Ahead of November 10 Goal Date as Commercial Launch Opportunity Comes Into Focus for NRx Pharma
- Immerse Yourself in the Historic Tochigi Autumn Festival, Celebrated Every Two Years Since 1874
- Resident Inspect Expands Virtual Property Inspections With AppFolio and Rentvine Integrations
- Unlocking the Next Phase of Growth with New AI Innovations; Targeting 2027 as Breakeven; Revenue Momentum Accelerates: ZenaTech (N A S D A Q: ZENA)
- AeroNet Deploys netElastic vBNG and CGNAT with Tarana Wireless to Deliver Scalable, Fiber-Class Broadband Across Puerto Rico
- New Atlas Maps the 38 States Behind Every Conversation
- Atlanta Company Launches Free, Ad-Free, Nonpartisan Voter Planning App for All 50 States Ahead of the Nov. 3 Election